The arterial waterways of global commerce are once again squeezing the heavy industrial world, and the aluminum market is rapidly reaching a tipping point. As maritime transit through the Strait of Hormuz deteriorates following a sharp resurgence of hostilities between the United States and Iran, major industrial players are sounding the alarm on a brewing global shortfall.
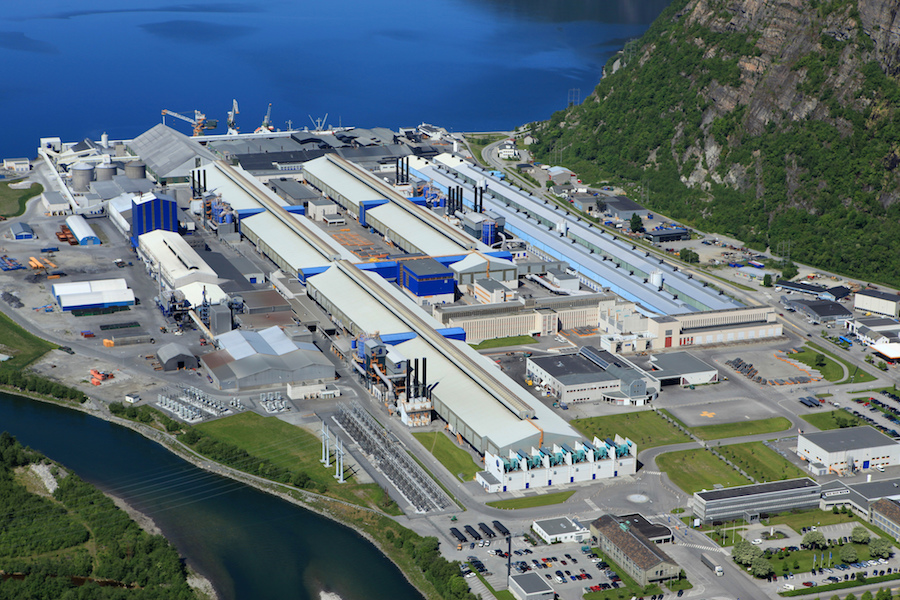
At the epicenter of the warning is European production titan Norsk Hydro ASA. Speaking on the widening fallout from the Persian Gulf conflict, Norsk Hydro CEO Eivind Kallevik highlighted how logistical bottlenecks are simultaneously throttling incoming raw material shipments to regional smelters and blocking outbound primary metal exports. With Middle Eastern operations accounting for nearly one-tenth of all global primary aluminum output, any sustained disruption threatens to fundamentally upend the supply balance.
“It’s quite clear that the situation has deteriorated quite rapidly,” Kallevik said, reflecting on the escalating shipping crisis. “The more protracted the situation in the Gulf is, logically the tighter the market will be globally.”
Prior to the latest maritime decay, Hydro had already modeled a looming global supply gap of 900,000 tons. However, a prolonged military engagement in the Gulf risks dragging the market into significantly deeper deficits. While Middle Eastern smelters race to secure alternative land routes and global peers attempt to scale up production, replacing the sheer volume of metal stranded behind the chokepoint remains a daunting industrial feat.
For now, an aggressive reordering of international trade routes has blunted the immediate shock. Chinese and Indonesian refineries have delivered unexpected supply boosts, while Western manufacturers spent the opening months of the year aggressively stockpiling inventory ahead of new European carbon import levies. Yet these safety buffers are rapidly thinning out across major European ports, leaving downstream fabricators dangerously exposed to fresh supply shocks as standard cargo flows stall.
“There was ample supply in many port inventories at the beginning of year,” noted Kallevik. “The acid test for the rest of 2026 is how many cargoes we get in to replenish those inventories.”
The economic feedback loops are already making themselves felt on balance sheets and trading desks alike. Driven by supply anxiety, London Metal Exchange benchmark prices spiked to $3,180 a ton in recent trading. For agile producers with operational flexibility, the market crunch has offered a lucrative upside. Norsk Hydro posted a 15% surge in Q2 output across its recycling division, pushing adjusted quarterly earnings to 8.92 billion kroner ($929 million)—handily outperforming analyst forecasts. But as port reserves drain and shipping channels remain constrained, the broader manufacturing sector faces a fraught second half of the year, where access to metal will depend almost entirely on how long the Gulf remains locked.
